Step 01
Define sampling methodology.
Set frequency, risk, quantity, occurrence, and coverage rules at the control level instead of rebuilding the approach in a spreadsheet.
AI-native Internal Audit + SOX
IABuddy connects planning, sampling, PBC, evidence, control testing, documentation, review, remediation, and reporting in one AI-native workflow.
Or start freeRevenue reconciliation
REV-04 — Q3 sample
PBC evidence
Waiting for evidence
Q3_Reconciliation.xlsx
Sample Q3 · Sheet 1
Source evidence stays attached to the sample.
Testing workspace
Ready to evaluate evidence
Illustrative product walkthrough
One connected audit workflow
Stop rebuilding context every time the work moves from a spreadsheet to an inbox, a shared drive, or a testing template.
Traditional workflow
The audit context breaks at every handoff
RCM
→ Excel
Sampling
→ Excel
PBC
Evidence
→ Shared Drive
Testing
→ Excel
Documentation
→ Word / PDF
Review
Reporting
→ PowerPoint
IABuddy
One governed system of work
Test
Evidence-linked testing
The control, sample, evidence, testing result, reviewer decision, and resolution remain connected from start to finish.
Plan → Sample → Request
Set sampling requirements by control frequency, risk, testing phase, occurrence, and coverage needs. IABuddy carries those requirements into sample selection and phase-specific evidence requests.
Step 01
Set frequency, risk, quantity, occurrence, and coverage rules at the control level instead of rebuilding the approach in a spreadsheet.
Step 02
Carry coverage requirements into walkthrough, interim, and year-end work so the team can see what each phase still requires.
Step 03
Use completed testing and the approved methodology to distinguish planned samples from the work that remains.
Step 04
Turn the outstanding sample need into phase-aware evidence-request drafts with the control and sample context attached.
Step 01
Set frequency, risk, quantity, occurrence, and coverage rules at the control level instead of rebuilding the approach in a spreadsheet.
Sampling Methodology
Risk and frequency based sample size
| Risk | Annual | Quarterly | Monthly |
|---|---|---|---|
| High | 1 | 4 | 5 |
| Medium | 1 | 2 | 3 |
| Low | 1 | 2 | 3 |
Coverage requirements
Quarterly · High risk → 4 samples
Include Q1 + Q4 in the annual testing coverage.
Step 02
Carry coverage requirements into walkthrough, interim, and year-end work so the team can see what each phase still requires.
Map Controls To Testing Phase
REV-04 · Revenue reconciliation
Annual required
4
Previously tested
2
Remaining
2
| Phase | Coverage | Samples | Status |
|---|---|---|---|
| Walkthrough | Process understanding | — | Complete |
| Interim | Q1 + Q2 | 2 | Tested |
| Year-End | Q3 + Q4 | 2 | To request |
Step 03
Use completed testing and the approved methodology to distinguish planned samples from the work that remains.
Map Controls To Testing Phase
REV-04 · Revenue reconciliation
Annual required
4
Previously tested
2
Remaining
2
| Phase | Coverage | Samples | Status |
|---|---|---|---|
| Walkthrough | Process understanding | — | Complete |
| Interim | Q1 + Q2 | 2 | Tested |
| Year-End | Q3 + Q4 | 2 | To request |
Step 04
Turn the outstanding sample need into phase-aware evidence-request drafts with the control and sample context attached.
Bulk PBC requests
REV-04 · Revenue reconciliation
Request type
Sample Request
Testing phase
Year-End
| Sample | Selected occurrence | Evidence |
|---|---|---|
| 3 | Q3 reconciliation | Preparation + approval |
| 4 | Q4 reconciliation | Preparation + approval |
2 samples · 1 control
Create Draft RequestsReview the draft before sending it to the control owner.
Evidence → Test
IABuddy evaluates evidence against each testing attribute, drafts sample-level results, cites the supporting source, and builds the testing record as the work happens.
Step 01
Open the sample evidence alongside the control context instead of losing the source in a shared drive while testing begins.
Step 02
Run each defined attribute at the sample level. The testing record is structured for the reviewer from the start.
Step 03
Results can retain a navigable file, sheet, page, cell, or sample-row reference so the conclusion can be checked quickly.
Step 04
As results are reviewed, the sample-level work and conclusion are already part of the memo rather than a separate documentation task.
Step 01
Open the sample evidence alongside the control context instead of losing the source in a shared drive while testing begins.
Q3_Reconciliation.xlsx
Sheet 1 · Sample Q3
Testing memo · REV-04
Revenue reconciliation
Step 02
Run each defined attribute at the sample level. The testing record is structured for the reviewer from the start.
Q3_Reconciliation.xlsx
Sheet 1 · Sample Q3
Testing memo · REV-04
Revenue reconciliation
Step 03
Results can retain a navigable file, sheet, page, cell, or sample-row reference so the conclusion can be checked quickly.
Q3_Reconciliation.xlsx
Sheet 1 · Sample Q3
Testing memo · REV-04
Revenue reconciliation
Source
Q3_Reconciliation.xlsx · Sheet 1 · Cell F24
Step 04
As results are reviewed, the sample-level work and conclusion are already part of the memo rather than a separate documentation task.
Q3_Reconciliation.xlsx
Sheet 1 · Sample Q3
Testing memo · REV-04
Revenue reconciliation
Source
Q3_Reconciliation.xlsx · Sheet 1 · Cell F24
Test → Document
Testing results, samples, evidence references, annotations, workpapers, comments, and conclusions stay connected—without rebuilding documentation after testing.
Testing phase
Sample Q3 · Testing memo
DraftedSample testing results
Preparation, approval, and balance agreement documented. Variance requires follow-up.
Evidence reference
Q3_Reconciliation.xlsx · Sheet 1 · F24
Conclusion · Draft
Additional support requested for the $475 difference. Pending auditor review.
Testing and documentation are the same workflow.
Exception → Resolution
When evidence does not support the control, IABuddy can turn the failed testing attribute into a reviewer-approved follow-up request, connect new evidence to a retest, preserve the original conclusion, and move unresolved issues into remediation.
Failed attribute
Variance exceeds threshold
AI drafts follow-up
Evidence gap and request language
Auditor reviews
Edit, approve, and choose recipient
Follow-up request sent
Request linked to the failed result
Additional evidence received
New evidence retains request context
Linked retest
Original conclusion remains preserved
Resolution path
Resolved
Retest supports the control.
Remediation
Unresolved issue moves into a governed action plan.
Choose a program view, then explore how context stays attached as work moves from planning to reporting.
RCM
Maintain risks, controls, ownership, attributes, and evidence requirements.
Select a stage to pause the guided view and inspect its product context.
Control library · Risk linkage
RCM
Reviewable AI
IABuddy applies AI inside governed audit workflows, where the evidence, methodology, reviewer decision, and history are part of the result.
Controls, risks, testing phases, samples, testing attributes, and evidence—not a blank prompt.
Results can reference pages, sheets, cells, files, and sample rows.
AI drafts, evaluates, annotates, and proposes. Auditors review and own conclusions.
Testing changes, reviewer comments, follow-ups, retesting, and remediation stay connected.
Process documentation
Turn narratives and walkthrough evidence into editable process maps. Link controls directly to the process and collect process-owner validation without rebuilding documentation in a separate tool.
Revenue reconciliation
Version 4 · Draft validation
Process owner
Prepare reconciliation
Control activity
REV-04 Review & approve
Finance system
Post approved entry
Control register
Linked risk: REV-R2
Move from preparation through detailed and general review while the sample, source evidence, memo, comments, and reviewer decisions remain available together.
Comments stay attached to the work—not buried in email.
Reviewer action
Live audit operations
Monitor testing, PBC requests, reviews, issues, certifications, and control status from one connected operating dashboard.
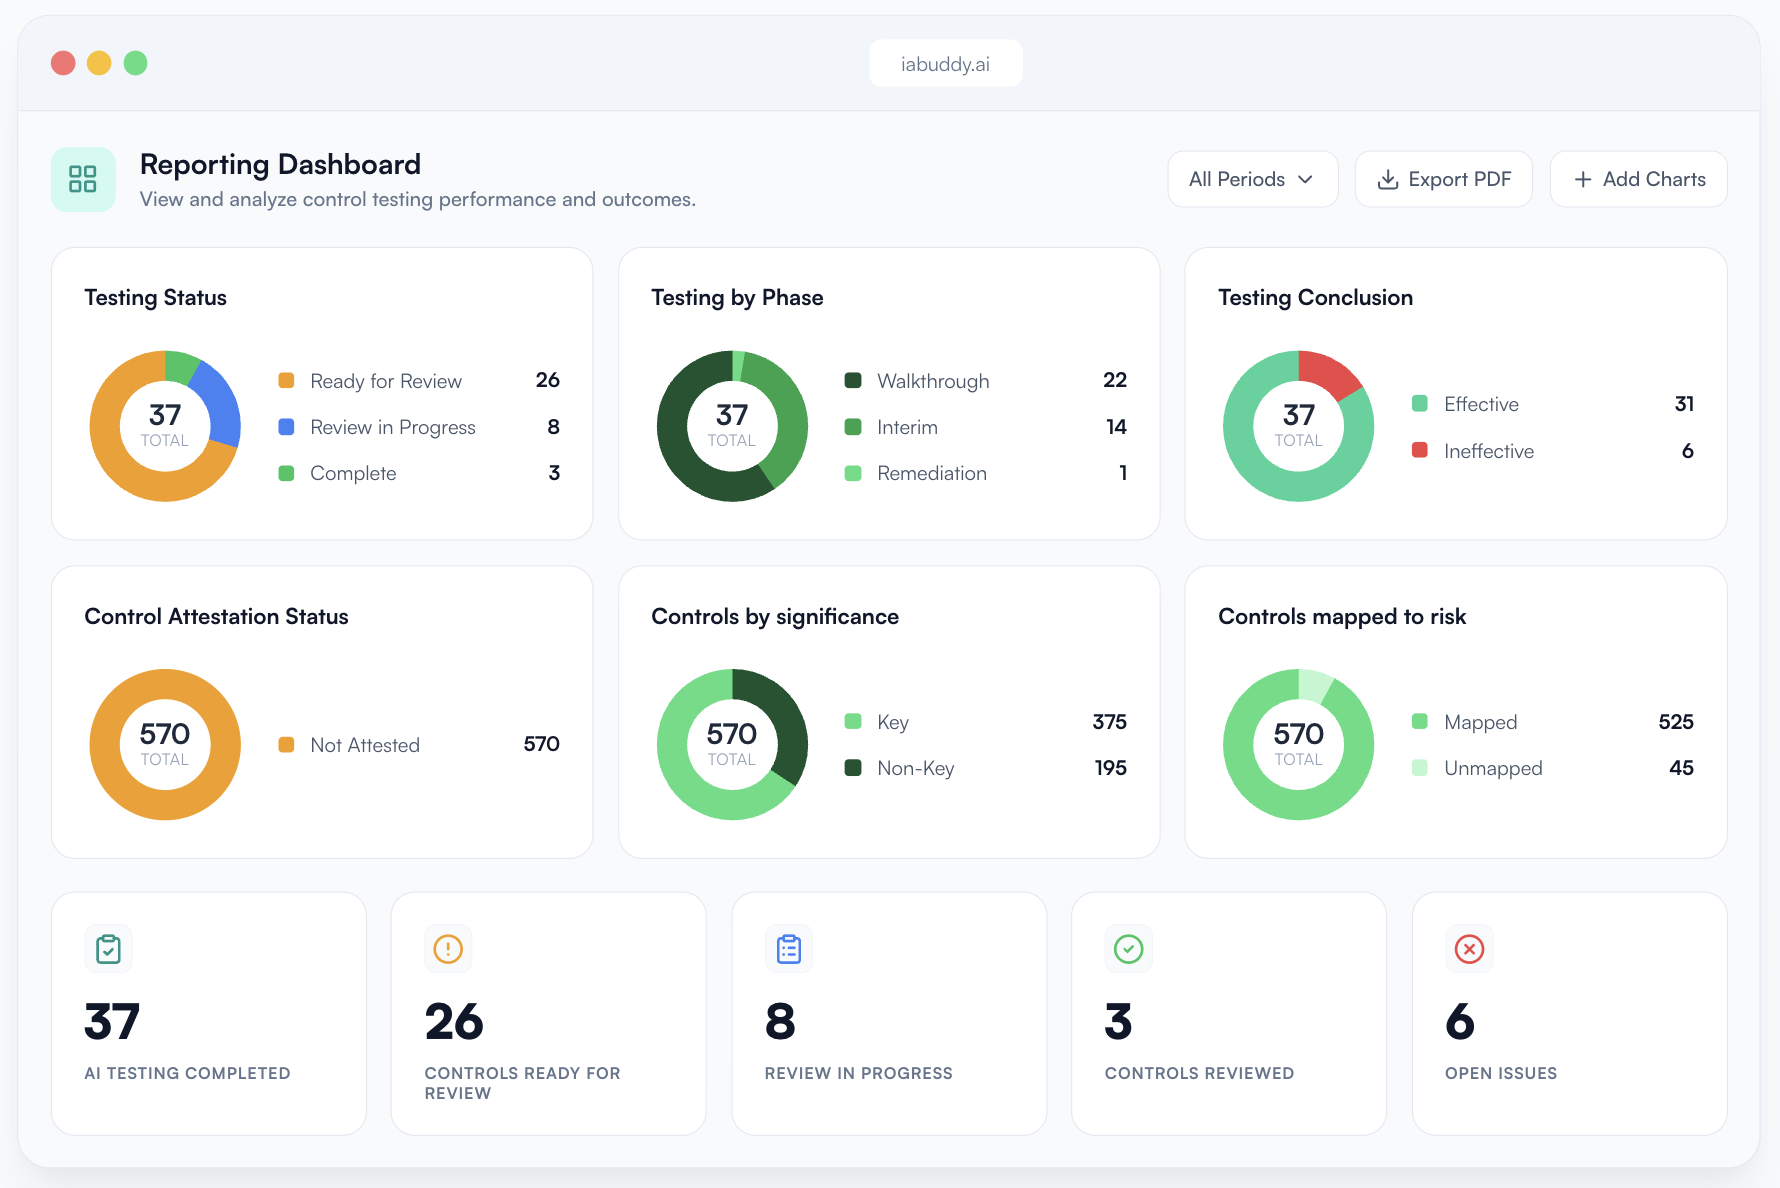
Product image uses anonymized demonstration data.
Purpose-built for lean Internal Audit and SOX teams, pre-IPO companies, recently public companies, and Controller-led compliance functions.
Solutions
Explore workflows designed around the operating reality of SOX, Internal Audit, and public-company readiness.
Run the annual SOX cycle in one connected workflow.
Explore solution 02From process understanding to testing, review, issues, and reporting.
Explore solution 03Build a governed control-testing operating model before spreadsheets become permanent infrastructure.
Explore solutionA practical view of product fit, workflow design, and where each platform may serve a team best.
IABuddy vs Workiva
Compare IABuddy’s workflow-led approach with a broad enterprise reporting and GRC platform.
Compare platformsIABuddy vs Optro
Compare purpose-built approaches to SOX program management and control testing.
Compare platformsIABuddy vs FloQast
Compare IABuddy with an accounting-operations platform that also supports compliance workflows.
Compare platformsGovern access to controls, evidence, testing, reviews, and changes with security practices built into the operating workflow.
See the connected workflow
We’ll show you how IABuddy takes it from sampling and evidence request through AI testing, documentation, review, and exception follow-up.